Thursday, February 10, 2011

Toyota. Buy, Buy, Buy!

Tuesday was a very sad day for me.  I have to admit I had started to believe that Toyota was just like any other huge corporation that had lost its way.   The lure to become, and remain number one in the auto industry was too much for them.  They had lost touch with customers, and worse still, they had put profits ahead of the safety, and lives of customers.

While I was suspicious of the media, and the agendas of the U.S. politicians, not to mention those of the U.S. auto industry, I never, for a moment believed that such unprecedented numbers of every-day people would misrepresent the difficulties they were having with their family automobile.  Now, I understood many, many people were walking away from home mortgages, but that seemed to me like a case of, "I can't pay what I don't have."  In the case of Toyota, they were actually blaming the car maker.  In addition, they were, and are, demanding compensation for problems which were, largely, not the fault of Toyota.

The National Aeronautics and Space Administration (NASA) has studied the problem and in every case, any difficulty caused by sudden acceleration would have caused the engine light to come on.  Only a handful of such cases exist according to the NASA studies.

Once again, we have to wonder what role the media has played in all of this.  As for our own media, the CBC in particular, I was sickened, when on that very same Tuesday, they chose to show the execution of one of the Egyptian protesters by, what appeared to be, the Egyptian police.  Is there not enough violence in this world already?  Is it any less violent to show such an act on national television than to commit the crime in the first place?  Are they trying to incite even more violence?  Do they feel they must go to these lengths to gain viewers?  Personally, in future, I will get my news from the internet, thankyou, CBC.  Just when I think people can't act any dumber...  Perhaps they have been watching their own newscasts for too long.

Having said all that, the thing that sticks in my memory about Toyota's difficulties is the chairperson of Toyota offering his sincere personal apology for not having listened to customers better!  Now this is the type of company I would be interested in.  Management plays a huge role in successful companies.  I can only contrast this with the likes of Firestone.  Firestone knew their tires were defective and that tire failures would result in people dying, but deemed it more cost effective to continue with production.  There were also other tire companies whose products I will never in my life-time buy again.  How's that for cost effective?  And, if I wouldn't buy their products, I'm not about to buy their stock.

The same goes for the likes of cigarette companies, or asbestos companies.  I know there are people in the media (and outside, for that matter), who believe the ends justify the means.  How can we invest in cigarette companies without condoning the sale of poison to people under the guise of free choice?  What type of greedy, mostly self-centred people should we think run those companies?  Do we really think they care about treating employees and shareholders fairly when they are prepared to poison their very own customers?  What about what it is costing you and I in health care expenses?  Should we feel that we can trust these people on any level?

For the free, capitalist system to work, we should reward the best companies that are able to achieve their greatness while upholding their ethical standards.  The only result of rewarding those who cheat and lie is more cheaters and more liers, especially when they are granted special status like "too big to fail".  I would rather make less money investing in honest and trustworthy companies and maintain my own integrity.  It isn't like I can buy it back again with the extra money I might otherwise make.  I say fire the politicians and bankers who created our current financial crisis, and stick with companies who have proven they can be trusted to be profitable while remaining fair, ethical and uncompromising - companies, as it turns out, like Toyota.

Do you believe the end justifies any means of obtaining it?  Why?

Tuesday, February 8, 2011

U.S. Unemployment Drops to 9.0 Percent!

I had to smile at the reactions to the non-farm payroll report on Friday.  While the U.S. economy added a lot fewer jobs than expected - well below the rate needed to accommodate new entries into the job market - the official unemployment rate dropped from 9.4 percent to 9.0 percent.  Apparently adjusting the numbers for seasonality includes factoring in the weather, of all things.

I have a suggestion.  Why don't we just say the unemployment rate is 4.0 percent, except for the people who are out of work because of the last recession?  Why spend time and money actually calling people, when we can just tell people what we want them to hear.  Perhaps we should try that with earnings estimates.  "We will stick with the numbers in our quarterly forecast as we would have met them had it not been for the case sales were lower than expected."  How about sporting events?  We can just give the better team a higher score since, normally, they would have won anyway.

My question is, at what point does massaging the numbers turn into rationalization, then denial?  I just heard Mr. Bernanke say U.S. economic policy was forcing fixed income investors to turn to "alternative" investments, but, no, that would not include commodities.  I understand the need to project positivity and hope, but we need to make financial decisions based on real facts.  There is real danger in fitting the facts to correspond to our outlook.

That is the takeaway to today's post.  Putting money into these volatile markets requires that we observe what is happening with an open mind, and protect our money accordingly.  We need to learn what to look for and have the discipline to act on that information.

Don't be misled by the propaganda of the day.  There is a world of market participants who are just waiting to take the money of people who do not have both, the discipline, and a system to protect them from their own emotions.  I even fear for the buy-and-holders when this commodity bubble bursts.  As hard as it is to watch the market go higher without me, I am not about to put new money into the current markets, expecting them to go much higher from here.  In my own case, I expect it will take a substantial correction in the indexes before conditions improve that much.

What about you?  Do you see opportunities in these markets?

Friday, February 4, 2011

The Effects of Qualitative Easing

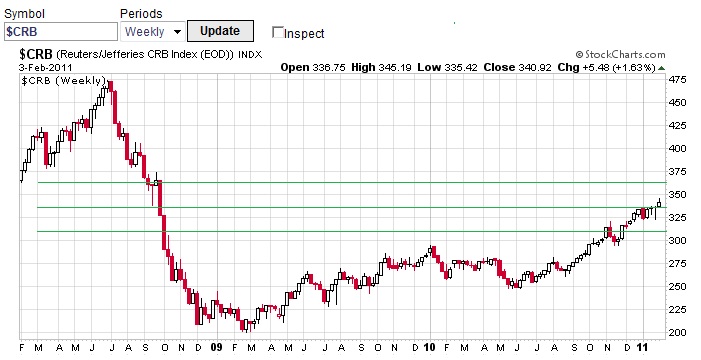
Click To Enlarge
I hadn't decided what this post should be about as I watched Mr. Bernanke say he did not feel rising commodity prices were being caused by U.S. monetary policy.  His take is higher prices result from too much growth in the developing countries.  He did admit that Qualitative Easing Round 2 was causing fixed income investors to look to "alternative" investments since yields were historically low.  (Just not commodities, I suppose).
 
Then came the story that commodity traders were making a huge bet on Thursday against base materials  - copper, lead, etc..  

Then I remembered a recent conversation I had regarding when the U.S. might have to ease up on what they are doing before riots the likes of Egypt started breaking out all over the place.

My point is, whenever the government starts to mess with the markets, it always, always, always, ends badly.  Do they not remember the cause of the financial crisis the world is, even now, trying to recover from?  As a kid, I think the expression was, "Two wrongs never make a right!"

I blogged a few days ago how I don't believe in forecasts, so while I cannot predict with any accuracy when it will happen, we can know from history that it will happen.  The chart above shows us the CRB Index.  It is an index which reflects the movement of global commodity prices.  The green lines I have drawn on the chart reflect the normal retracement levels for a typical correction.  Like dropping a golf ball, or a basketball, or any rubber ball, the bounce is somewhat predictable.  Does that mean the index can't go higher than the highest green line?  No, but probability says that it normally won't.  You can see why traders are preparing for a reversal in commodity prices.

There are a couple of reasons why that might not happen.  First, the government stimulus may not have run its course, as yet.  Mr. Bernanke did not rule out the possibility of QE3 in his presentation.  Personally, I don't think they know what else to do.  Secondly, we are in the middle of the period of time when materials, metals, and mining tend to do their seasonal best.  The third reason would be what I said about things ending badly.  We are close to the point when we would expect a reversal.  The longer the prices run up, the worse the result, both to the world economy, and to the eventual crash.

I can hear it all now.  Once QEn (where n equals infinity) no longer has a stimulative effect and things come crashing down around our ears, the best and brightest minds(?) on the planet will tell the cameras with completely straight faces, that despite riots in the streets protesting the unaffordability of food and fuel, nobody knew a crash might happen!  Sound familiar?

I'm not trying to scare anyone out of the market, but I am suggesting a great deal of caution out there!    

Thursday, February 3, 2011

Portfolio Update

I am not a financial advisor, nor do I hold any designations within the financial services industry except one.  While working in the life insurance industry I did obtain the designation of Fellow of the Life Management Institute (FLMI) which means I have passed a series of exams relating to the life insurance industry.

My story is similar to the fisherman who lived in a small shack located in a tropical paradise. He would take people who knew little, if anything about fishing on guided tours of the best fishing spots.  On one such occasion, one of those people asked him why he didn't borrow some money and buy more fishing boats?
"Oh, and then what?" the fisherman asked. 
"Well, you could grow the size of your company and make lots of money," the other said.
"Oh, so then what?" asked the fisherman. 
The person said to him, "You could buy a bigger house, faster boats, and save for your retirement." 
Again, "Oh, so then what?" asked the fisherman. 
"When you are ready to retire," the other said, "you can sell your company, buy your dream home, move there, and live happily ever after!" 
"But," protested the fisherman, "That is what I already have!"

I understand having various industry designations would give me more credibility with people who don't already know me, but I remain unconvinced they would make me better at what I do.  Personally, I believe most "how to" advice regarding stock markets is, largely, marketing advice.  I don't want lessons in marketing. I want to help others who are interested in having more money.  Since I am not legally qualified to do so, rather than offer stock picks, I will reveal my methods and returns so others can decide whether, or not, I do have any credibility.  I will help those I can, and not worry about the fact others will reject (and criticize) my ideas.

Indeed, I welcome constructive criticism.  The quickest way to improve is by learning from the experience of others.  Although I have learned much over many years, I look forward to the thrill of future discovery.

I am not a day-trader, nor am I an advocate for buy-and-hold.  With that in mind, I will post monthly portfolio updates.  Earlier I wrote about setting aside an amount to be invested in the name of charity.  That amount is determined by the returns on my advanced market timing model.  I will also update the returns of the basic timing model (seen here) .

One month return for TSX @ Jan. 31, 2011 = 1.01 percent
One month return for Basic Timing Model using XIU = 1.5 percent
One month return for Advanced Timing Model (my returns) = 4.1 percent
Money for charity = $411.27

Tuesday, February 1, 2011

What Are ETF's?

ETF stands for Exchange Traded Fund.  When I wrote about my basic market timing model, I mentioned the purchase of an ETF which tracked the total stock market rather than a mutual fund.  Before I talk about ETF's I would like to talk, first, about the problems I have with mutual funds.

Most mutual funds are actively managed, where a fund manager decides what to include in the fund according to the prospectus which defines the types of investments to be held.  There are equity mutual funds, fixed income mutual funds, and money market mutual funds.  Many have sales fees, either when I buy, or when I sell.  They charge a management fee, and deduct certain costs from the returns they generate.  Mutual funds pay a commission to the person who sold me the fund.  While there are a couple of good reasons to buy a mutual fund, generally, the cost of doing so is the reason I am not a fan.  Just to be clear, I am not a financial advisor, or anything of the sort, either.  In a case of I can buy better, but I can't pay more, most funds, because of the expenses involved tend to under perform the market.  One's that outperform rarely do so for long periods of time.  Guessing which mutual fund to own is a bit of a mug's game.

ETF's, on the other hand, tend to mirror a particular index, or commodity.  Since there is usually nobody picking what to include and what not to (that has already been determined by the index), the charges to me for fund management are less.  What that also means is when the index goes lower, so does the ETF, by an equal amount.  There is nobody trying to slow the decline.

They are called exchange traded funds because the shares trade on a stock exchange in the same fashion as other stock equities.  When I buy shares in the fund, I pay a commission fee, instead of a sales charge.  The management expenses are deducted prior to the share's value being determined.  If my shares go up ten cents each, then that means I made ten cents after the fund company has taken their portion.

There is a difference between regular shares and ETF shares.  With regular shares I purchase shares in one company at a time.  With ETF's I buy a basket of shares (of whatever makes up the underlying index), or contracts based on commodities.  A few ETF's allow me to buy the actual underlying commodity itself, with the fund manager having to store it for me.

Another difference is one of supply and demand.  A company offers a number of shares in the company to raise money.  ETF's are bought and sold from a float which is for most purposes, practically limitless.  I do not need to be overly concerned with supply and demand, as those constraints apply to the price of the underlying index, or commodity.

For people who have not heard about ETF's from a financial advisor, it is likely because advisors do not make any money when recommending the purchase of an ETF.  They do when selling mutual funds, but not for ETF's.  Since they trade like stocks, purchasing ETF's is seen to be more for the sophisticated investor, and less so for the beginner.  To avoid full service brokerage fees, I also need my own discount brokerage account online.

When starting out, I looked at purchasing widely based ETF's which performed as closely to the actual TSX as possible.  Sector, and specialty funds came later only after I gained more experience.  Claymore, Ishares, Horizons, as well as many of the Canadian banks have ETF's which are bench marked to the TSX.

Again, learning to manage my own funds took a little time and effort, so I started by "paper" trading without plunking down any actual money, and then started very, very small.  By small, I mean no leveraged ETF's - ETF's that return a multiple of the underlying index (i.e.: two times, or three times) until I gained some experience and understood what they were and how they worked.

I can make more by earning higher returns from my investments, or better still, by simply avoiding many expensive mutual funds.

Monday, January 31, 2011

2011 Economic Forecast

I don't place much faith in economic forecasts, save one - the outlook of management of the company I own stock in.  They are holding the order book, so if they think it is going to be a good year, then that helps me to have confidence in their numbers.  Good management rarely surprises on their numbers. 

Having said all that, I recently attended a venue in which Craig Alexander, the Senior VP and Chief Economist at TD Bank gave us his view of the state of the economy.  He emphasised at different times the continuing volatility in the markets.  As if on cue, Egypt is making the news and having an affect on markets, especially the price of oil.  Here are some of the highlights. 

The global economy is, currently, a two-speed economy.  Despite our interconnectedness, the developing economies are experiencing fast growth, while the developed economies are experiencing slow growth.

Inflation is growing in China, not so much in the Western World.

A slowing in China's economy would be favourable; a hard landing would not be.

China has the ability to reverse the course of its economy.

We are at an inflection point today where the so-called developing economies are surpassing the so-called developed economies.

In Europe, real problems existed before the financial crisis, which were made worse.

The European bailout fund is not large enough to cover all possible defaults.

One method to fight recession is the devaluing of the currency; Europe lacks this ability

The normal recession is caused by high inflation and high interest rates.  The following contraction causes rates to fall and growth to resume.  This time IS different (to the normal recession).

Compared to other financial crises, the U.S. situation is on track, with recovery taking 7 quarters (the one we are in now).

The total (as opposed to reported) inventory of houses in the U.S. market is currently 19 months.

In Canada, the main loss of jobs was in manufacturing; the recovery in services, and government.

Canadian housing market is NOT in a bubble, simply a response to supply and demand.

While Canadian household debt is high, a lot of it can be attributed to the large number of first-time home buyers recently entering the Canadian housing market.

So, what does that mean?

Braking in China.

Continued volatility, especially in Europe.

One and a half percent growth in Europe.  Boom in northern Europe, including Germany.

Default on debt by a European country is still likely.

No double dip, and no depression.

Recovery in the U.S. housing market will take 4 or 5 years.

Three to three and a half percent growth in the U.S. economy.

U.S. employment will rise slowly, as will inflation.

U.S. interest rates likely to rise in second half of 2012.

Canadian growth of two and a half percent.

Canadian exports to the U.S. could take 10 years to get back to "normal".

Slight drop in Canadian housing market.

Strong business investment.

Bank of Canada interest rate hike in July, 2011.

All of this would suggest cash and cash equivalents will return less than the rate of inflation.  Good corporate bonds at the shorter durations are most favoured in this environment.  Growth in U.S. equities is expected to be in the high single digits, with low double-digit growth in Canadian equities.  Most of all, continued high volatility in the financial markets.

Friday, January 28, 2011

Timing The Market


Click to enlarge
The new FCIC report came out yesterday with blame for everyone as to who caused the financial crisis.  Most deny any wrongdoing by saying, "Nobody knew!"  Do they mean to tell me that the actuaries at AIG who are trained in probability analysis figured there was a zero percent probability that the U.S. housing market might correct?  Are they telling me the rating agencies whose job it is to assess the worthiness of a security had no idea products based on mortgages from the U.S. housing market might be less than AAA?

I would have a difficult time proving anyone is that stupid.  Assuming they aren't, then doesn't it go to follow they are not telling us the truth?  Why would they lie to us?  Could it have to do with how they were  being compensated and by how much?  I have read stories of traders who barely understood how to spell the word market (okay, I'm exaggerating) were pulling in multiples of six figure incomes.  Would you lie for a million dollars?  I know some people who would.  I think we all do.

What if I told you some of these people are the same people who are telling us we cannot time the market?  Are you surprised?  Please look at the chart.  This is a very basic chart showing the monthly price ranges of a security that trades on the TSX.  The ticker symbol is XIU.  It is an Exchange Traded Fund (ETF) that derives it value from the Toronto Stock Index.  In other words, as the TSX goes up, so does the ETF by the same percentage.  Likewise when the TSX goes down.

Also shown is the line which, basically represents the 200-day moving average.  Take the average price of the XIU for the last 200 days and draw a dot on the chart.  Take the 200-days one day prior to that and do the same.  And so on.

How do I use that information?  Once a week, I look to see if our price is above, or below the line.  When it has crossed from below, I buy XIU.  When it has crossed from above, I sell XIU.  Doing that from even the peak of the market in the year 2000, and I would likely have more than doubled my return since then, even after paying any commissions.  A little better than that of the "buy and hold" mutual fund owners, wouldn't you say? 

I'm sure I could show that to some children and they would be able to do it for themselves.  Do you really think your financial advisor has never seen this?  Can they really be that dumb?  Of course not.  The reason they don't tell us about it is because they won't make any money if that's all we do.  More importantly, the company they work for will only make a lousy little commission.  Now, we couldn't have that!  Now I'm not saying I will double my money every ten, or so years, but I like the returns a lot better than a "buy and hold" approach.

Still, I can hear the protests.  "But you're not diversified, the TSX isn't always going to do so well, nobody can predict the future", etc., etc., etc.  Do I really think the world is going to stop growing?  Does the world have too much oil, copper, wood, grain, fertilizer, water, that nobody is ever again going to buy anything from a free, democratic, trading country like Canada?  Maybe Australia will fill all the needs!  Come on folks!  I'm not saying we have to put all of our money into the TSX, and even though it may represent only three percent of the companies in the world, it is three percent of the best financial, mining, and energy companies anywhere on this entire planet!

There is no doubt in my mind there will come a time when what Canada has to offer will no longer be so desired.  Until then, why make it more difficult than it needs to be?  Simplify, simplify, simplify.  Look past the elaborate smoke screens and misinformation and marketing ploys.  There are any number of companies who want to mislead us in order to lighten our pockets.  Never mind a million dollars, there are people who will lie for a lot less than a million dollars.  After looking at this chart, do you really mean to tell me there is no timing the market?!?